INDEPENDENT RETIREMENT-INCOME ANALYSIS
Secure Your Retirement Future
Navigate retirement-income decisions with an objective review of annuity contract features, costs, and trade-offs. We help pre-retirees and retirees evaluate whether an annuity may fit their strategy before committing to a product.
Objective evaluation · Transparent contract review · No sales pressure
MARKET VOLATILITY & LIFETIME CASH FLOW
Navigating Market Uncertainty
For decades, traditional financial planning centered almost exclusively on asset accumulation. Yet the transition into retirement introduces a fundamentally different set of dynamics: managing decumulation during periods of economic fluctuation where sequence-of-returns risk can permanently alter portfolio longevity.
When retirees must liquidate volatile equity positions during market downturns to cover ongoing living expenses, portfolio recovery becomes mathematically constrained. Establishing an insulated, contractual income floor separates essential lifestyle cash flow from equity market volatility—delivering clarity, emotional poise, and mathematical resilience to your broader retirement framework.
STANDARDS OF OBJECTIVE REVIEW
Our Objective Methodology
A clinical, mathematical evaluation process built to eliminate product bias and stress-test every income scenario against actual market realities.
Fiduciary Oversight
Every recommendation is legally bound to your best financial interests, completely decoupled from carrier quotas or sales incentives.
Personalized Math
Custom actuarial modeling that maps your precise assets, spending horizons, and tax profiles to isolate your exact guaranteed income floor.
Radical Objectivity
Unbiased market scanning across dozens of top-rated institutional carriers to contrast genuine contractual guarantees against alternative structures.
Independent analysis with zero sales obligation or pressure.
STRATEGIC METHODOLOGY
A Data-Driven Approach
We replace retail sales rhetoric with institutional analytics. Every contract is systematically stress-tested against contractual minimums, operational expenses, and insurer balance sheets.
STAGE 01 / QUANTITATIVE SCREENING
Objective Software Screening vs. Market Noise
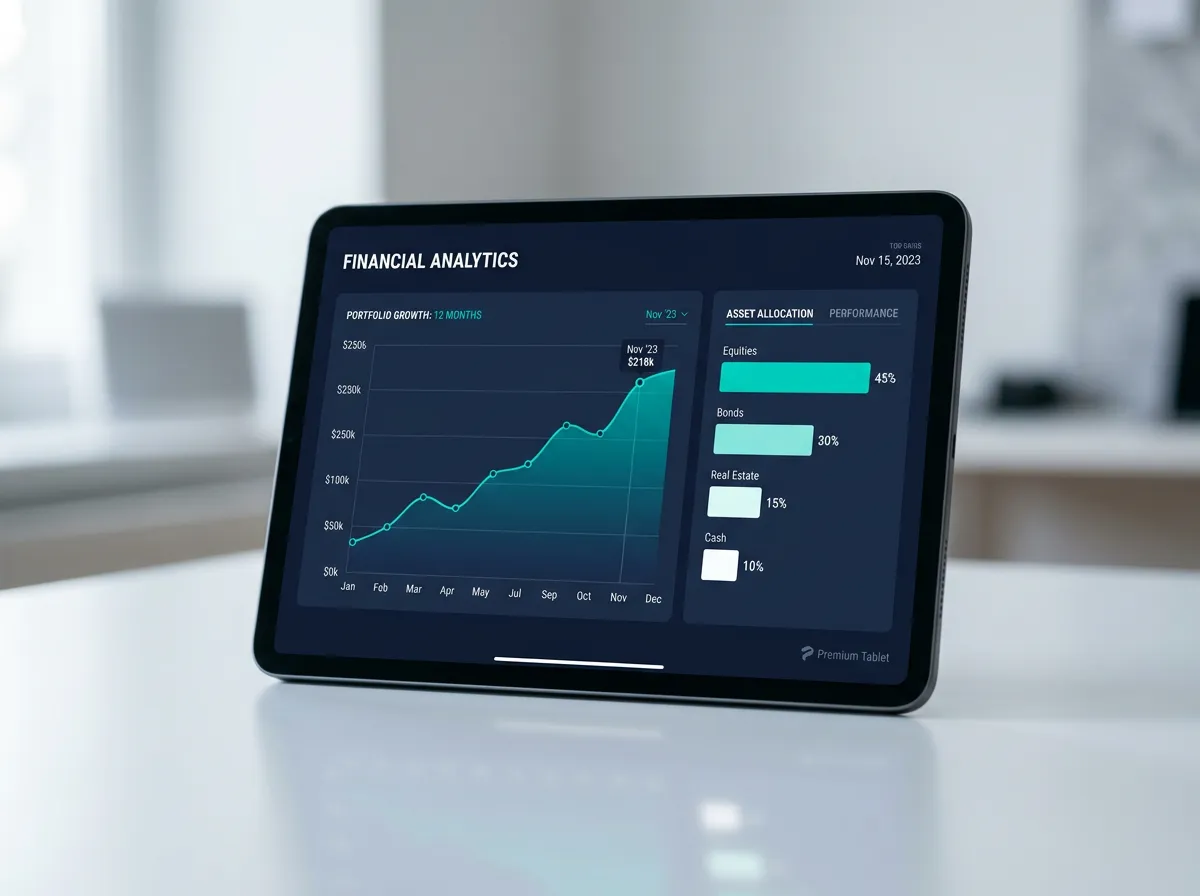
Retail annuity recommendations often reflect commission incentives rather than mathematical suitability. Our proprietary screening engine filters through thousands of active product series across the national marketplace, filtering out volatile index caps and unrealistic non-guaranteed illustrations.
- Exclusion of non-guaranteed bonus traps and misleading multiplier riders
- Mathematical stress-testing against 30-year historical inflation cycles
- Carrier capital surplus verification with independent solvency rating audits
STAGE 02 / CONTRACT REVIEW
Fiduciary Compliance and Fee Transparency
Every proposed contract is reviewed to clarify rider costs, administrative charges, and surrender provisions before you decide whether to move forward.
- Contract-level review of costs, riders, and surrender provisions
- Plain-English explanation of guarantees and limitations
- Liquidity considerations and withdrawal restrictions to review before moving money
Institutional screening across 40+ independent carriers. Unbiased and carrier-agnostic.
PORTFOLIO ARCHITECTURE COMPARISON
Fragmented Assets vs Structured Income
Transitioning from market-dependent withdrawal rates to an engineered, reliable floor shifts sequence-of-returns risk off your balance sheet.
THE CONVENTIONAL MODEL
Fragmented Asset Allocation
Ad-hoc accounts requiring active liquidations regardless of equity market drawdown cycles.
- Full exposure to sequence-of-returns volatility during distribution phase
- Uncertain annual cash flow requiring constant liquidation re-calculations
- Stress of managing variable systematic withdrawal rates (3% - 4% rule)
- Principal decay risks during prolonged equity market corrections
THE OBJECTIVE EVALUATION BLUEPRINT
Engineered Income Architecture
Contractual guarantees establish an enduring income floor while leaving discretionary capital free to grow.
- Guaranteed contractual income floor insulated from market volatility
- Predictable monthly distributions deposited directly to your institution
- Elimination of emotional decision-making during severe economic cycles
- Growth sub-portfolios protected from forced fire-sale liquidations
EDUCATION & CLARITY
Complex Vehicles, Simplified
Retirement contracts are often obscured by 80-page prospectuses and proprietary industry jargon. Here is what matters in plain language.
Guaranteed Lifetime Income (The Floor)
A contractual agreement where an issuing insurer guarantees predictable monthly payments for as long as you live, regardless of market volatility or personal longevity. It functions like a private pension stream.
Principal Protection (Zero Loss Shield)
Your initial deposit cannot decline due to equity market corrections. In fixed or indexed structures, your base balance is insulated against downturns while retaining defined upside crediting formulas.
Rider & Liquidity Parameters
Optional policy provisions (riders) can add inflation adjustments, enhanced death benefits, or chronic care multipliers. Most contracts also permit up to 10% penalty-free annual withdrawals for emergency needs.
Analytical Principle: Fixed contractual yields remove the burden of market timing from everyday essential living expenses.
OBJECTIVE CLASSIFICATION & RISK PROFILES
Comparative Analysis: Fixed, Indexed & Variable Structures
A compliance-aligned breakdown of principal guarantees, growth mechanics, liquidity constraints, and fee disclosures across primary contract categories.
CONSERVATIVE PROFILE
Fixed Annuity (MYGA)
Contractually guarantees a stated annual interest rate for a defined period (typically 3 to 10 years), backed by the insurer's claims-paying capability.
KEY ATTRIBUTES & ADVANTAGES
- Full principal protection against equity market loss
- Guaranteed compound rate of return for contract duration
- Tax-deferred accumulation on non-qualified deposits
- Predictable baseline for scheduled income generation
RISKS & CONTRACT CONSTRAINTS
- Purchasing power risk during elevated inflation periods
- Surrender charges apply to early excess withdrawals
- Return capped at contractually agreed base rate
HYBRID BALANCED PROFILE
Fixed Indexed (FIA)
Credits interest linked to external market indices (e.g., S&P 500) up to predetermined caps or participation rates, with an absolute 0% contract floor.
KEY ATTRIBUTES & ADVANTAGES
- 0% floor guarantees zero negative index returns on principal
- Annual reset locks in earned gains permanently
- Upside participation exceeds conventional fixed instruments
- Optional lifetime income riders (GLWB) available
RISKS & CONTRACT CONSTRAINTS
- Gains capped or adjusted via participation/spread limits
- Dividends from underlying indices are not credited
- Optional rider fees may deduct from cash surrender value
GROWTH & RISK PROFILE
Variable Annuity (VA)
Allocates premiums directly into sub-accounts (stocks/bonds). Account value fluctuates directly with performance; investment risk rests entirely with the contract holder.
KEY ATTRIBUTES & ADVANTAGES
- Uncapped market upside potential via equity sub-accounts
- Tax-deferred rebalancing between investment options
- Sub-account diversification across asset classes
- Available death benefit guarantee riders
RISKS & CONTRACT CONSTRAINTS
- Direct market loss exposure; principal is not guaranteed
- Higher ongoing internal expenses (M&E, admin, fund fees)
- Market volatility directly affects income distribution value
Regulatory Disclosure Note: Guarantees are subject to the financial strength and claims-paying ability of the issuing life insurance company. Annuity contracts are long-term insurance vehicles intended for retirement. Early withdrawals prior to age 59½ may incur a 10% IRS penalty in addition to ordinary income tax. Variable annuities are sold by prospectus.
OBJECTIVE FRAMEWORK
The Decision Journey
A structured evaluation process designed to clarify fit, trade-offs, and next steps based on your objectives.
Income Gap Audit
Quantifying essential vs. discretionary expenses to map guaranteed baseline deficits.
Vehicle Stress Test
Evaluating contract riders, inflation protection, and fee structures under severe drawdowns.
Tax Integration
Structuring non-qualified, IRA, and Roth distributions for optimal lifetime tax efficiency.
Execution Blueprint
Receiving a conflict-free report detailing clear allocations or the recommendation to forgo annuities.
Objective review : No sales pressure : Clear discussion of next steps
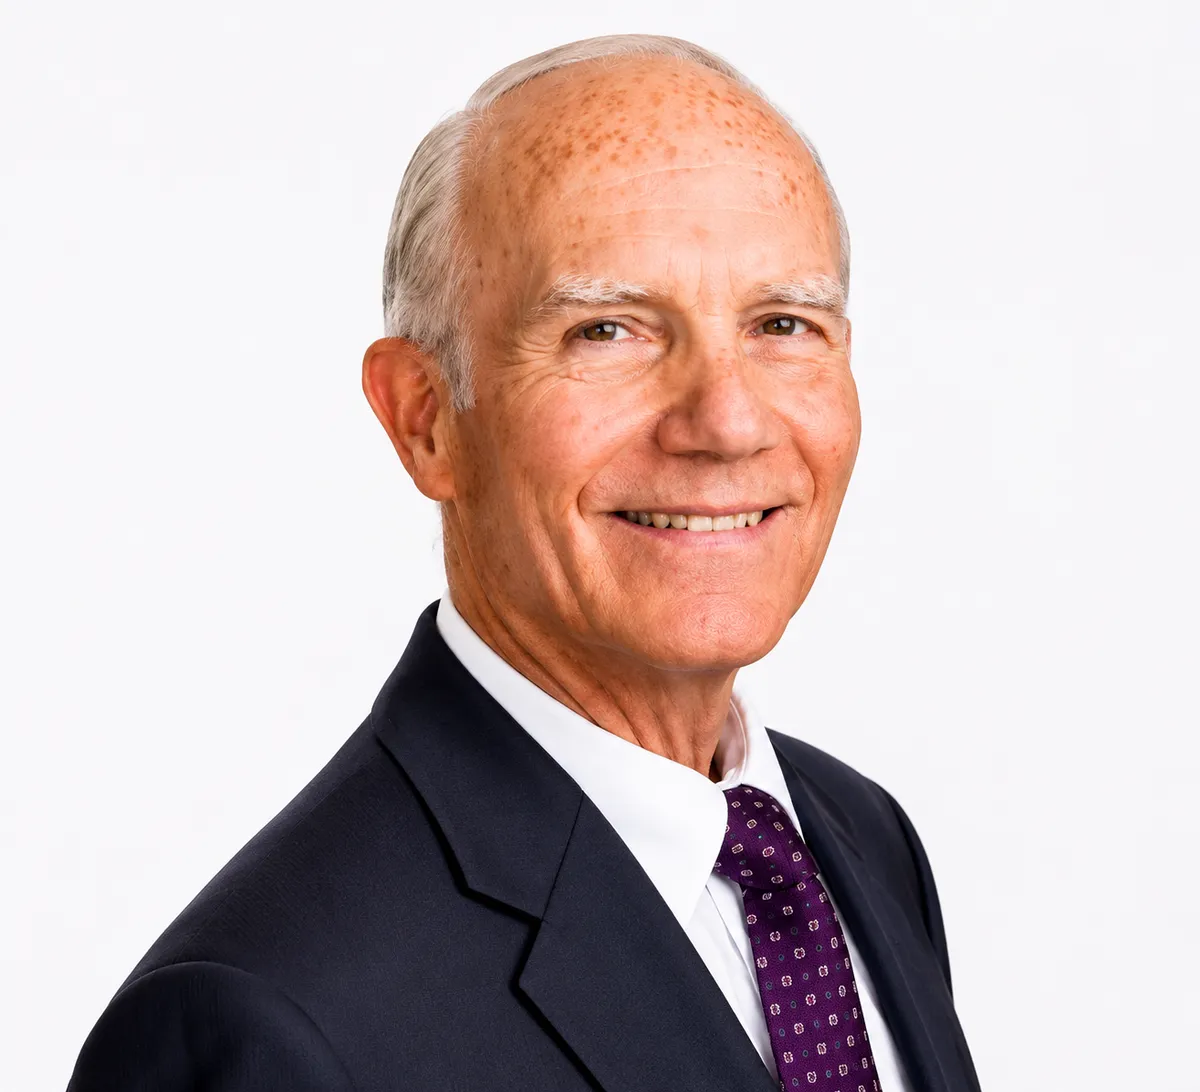
MEET YOUR ADVISOR
Experience Behind the Analysis
Denney Pugmire, Life Insurance Advisor
Utah-Licensed CPA · Master's Degree in Accounting · U.S. Army Veteran, Captain
Denney Pugmire brings accounting, insurance, and military experience to retirement-income planning.
With a Master's degree in Accounting, a Utah CPA license, and experience as a U.S. Army Captain, Denney approaches retirement planning with an emphasis on understanding the numbers, the contractual details, and the objectives behind each financial decision.
Denney is licensed in 19 states and holds NPN #6236605.
“Understand the retirement objective first. Evaluate the available strategies second. Make the product decision last.”
The goal is to help clients understand the relevant costs, guarantees, restrictions, risks, and trade-offs before making an insurance or retirement-income decision.
- MASTER'S DEGREE IN ACCOUNTING
- UTAH-LICENSED CPA
- U.S. ARMY VETERAN - CAPTAIN
- LICENSED IN 19 STATES
Licensed in 19 States
The goal is to help clients understand the relevant costs, guarantees, restrictions, risks, and trade-offs before making an insurance or retirement-income decision.
View Licensed States
Alaska · Arizona · California · Florida · Hawaii · Idaho · Massachusetts · Michigan · North Carolina · Nevada · Ohio · Oregon · Pennsylvania · South Carolina · Texas · Utah · Washington · Wisconsin · Wyoming
30 minutes · Confidential · No obligation
Phone: 801-390-0887
Website: https://denpuglifecoverage.com/denpuglifeinsurance
STANDARDS & REGULATORY DISCLOSURE
Fiduciary Due Diligence
We focus on a transparent review of goals, contract terms, and trade-offs so you can make a more informed decision.
Contract & Disclosure Review
Legally bound by the Investment Advisers Act of 1940 to act solely in your best economic interest at all times, eliminating product-sales quotas and proprietary dealer markups.
Series 65 & Advisory Registration
Maintained by licensed Investment Adviser Representatives with complete Series 65 qualification and active state regulatory registrations searchable via FINRA BrokerCheck.
100% Conflict Disclosure
Full Form ADV Part 2A delivery prior to engagement, outlining fee structures, carrier independence, and complete structural transparency across every contract analysis.
Institutional Multi-Carrier Due Diligence
Evaluations encompass AM Best, S&P, and Moody's solvency metrics across 40+ leading carriers, strictly auditing capitalization reserves and contractual yield stability.
GOVERNANCE STANDARD
Institutional Vetting Framework
Every recommendation is algorithmically filtered and signed off by two credentialed fiduciaries before delivery.
PROCESS-BASED QUALITY CONTROL
Verifiable Objectivity
Our advisory models remove individual bias through automated contract auditing across the entire institutional landscape, coupled with mandatory multi-analyst verification.
- Proprietary Actuarial Filtering Algorithm: Screens 2,400+ annuity contracts across 85 tier-one insurance carriers daily, stress-testing participation caps, spread charges, and surrender lockups.
- Mandatory Multi-Advisor Peer Review: Every retirement income blueprint must pass independent review by two credentialed fiduciaries before presentation to ensure zero confirmation bias.
- Structural Fee & Rider Drag Audits: Quantifies internal cost layers, rider charges, and inflation drag to isolate true net-guaranteed yield versus gross illustrative claims.
- Unbundled Compensation Transparency: Pure conflict-free analytical architecture operating strictly without proprietary product quotas or carrier-sponsored payout incentives.
TRANSPARENT CONSULTATION PROCESS
What Happens When You Book?
A structured, four-stage evaluation designed to give you greater clarity around your retirement-income strategy—with no product sales obligation.
Schedule
Choose a convenient 30-minute time for your retirement-income analysis.
Prepare
Complete a short questionnaire about your retirement goals, assets, income needs, and priorities.
Review
Meet for a focused consultation to discuss your retirement-income objectives and the questions that matter most.
Next Steps
Review the key considerations, questions, and potential next steps based on your situation.
30 minutes · Confidential · No obligation
Independent analytical review · No product sales obligation · Transparent discussion of contract terms
TRANSPARENT & UNBIASED
Our Objective Methodology
Objective analysis designed to review fees, liquidity restrictions, and income features without sales pressure.
Fiduciary Oversight
Review focuses on contract terms including surrender charges, internal expenses (when applicable), and carrier financial strength considerations.
Personalized Math
Custom actuarial cash-flow modeling stress-tests inflation scenarios, sequence-of-returns risk, and liquidity demands to map guaranteed lifetime income precisely to your timeline.
Radical Objectivity
Complete transparency regarding where annuities fit and where they do not. If an alternative vehicle or lower-cost index strategy serves your retirement better, our analysis explicitly shows it.
Confidential evaluation · No sales pressure · Independent analysis
TRANSPARENCY & DISCLOSURES
Compliance & Disclosures
Clear disclosures and explicit terms of engagement. We prioritize clarity around compensation, contractual liquidity terms, and scope of services before any recommendations are made.
Direct Inquiries: For institutional audit or written compliance documentation, contact our regulatory team directly.
How are advisors compensated when analyzing or implementing an annuity strategy?
Compensation depends on the services provided and whether an insurance product is implemented. If an insurance or annuity product is implemented, the applicable compensation and costs are disclosed as part of the process. This consultation is educational and designed to help you understand contract terms and trade-offs.
What are surrender charge periods and liquidity provisions?
Many annuity contracts include surrender periods, withdrawal restrictions, or charges if money is taken out early. Terms vary by contract. Part of the review is understanding your liquidity needs and how any restrictions could affect you.
What is the legal difference between a fiduciary standard and insurance suitability?
A fiduciary standard generally refers to a legal obligation that applies in certain advisory relationships. Insurance suitability standards are different and focus on whether a product is appropriate at the time of sale. If investment advisory services are provided under an executed advisory agreement, fiduciary obligations apply to that advisory relationship. For insurance transactions, applicable insurance standards apply.
How do fees, caps, and optional riders affect contract outcomes?
Fees and contract economics vary by annuity type and optional benefits. Items to review can include rider charges, spreads, caps, participation rates, and administrative fees (when applicable). We review how these terms can affect outcomes under different scenarios.
How are annuity guarantees backed, and what happens if an insurer has financial trouble?
Annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. State guaranty associations may provide limited protection subject to state law and limits. Part of the evaluation is reviewing the issuing insurer and the contract terms.
OBJECTIVE RETIREMENT-INCOME EVALUATION
Take the Next Step
Gain clarity on guaranteed lifetime income options, contractual protections, and non-proprietary comparisons customized to your retirement timeline.
Independent analysis. Educational, contract-aware review with no sales obligation.
FIDUCIARY DISCLOSURES & REGULATORY COMPLIANCE
Consultation Strategic Wealth Partners LLC | Institutional Advisory Services | Registered Office: 100 Montgomery Street, Suite 2200, San Francisco, CA 94104 | Direct Compliance Desk: (800) 419-7820 | [email protected]
Advisory & Fiduciary Standard: Advisory services are offered through Consultation Strategic Wealth Partners LLC, a Registered Investment Adviser. Fiduciary obligations apply strictly when providing individualized investment advisory services under an executed advisory agreement. Insurance products, including fixed index and multi-year guaranteed annuities, are offered through affiliated licensed insurance agents and independent agent partnerships.
Guarantees & Insurance Underwriting: Annuity contracts are long-term financial vehicles designed specifically for retirement income accumulation and distribution. All guarantees, including principal preservation, interest credit floors, lifetime income riders, and death benefits, are backed solely by the financial strength and claims-paying ability of the issuing insurance carrier. Guarantees are not insured by the FDIC, NCUA, SIPC, or any federal government agency.
Surrender Charges, Fees & Liquidity Constraints: Annuities may be subject to surrender charge periods, market value adjustments (MVA), premium bonus recapture provisions, and early withdrawal penalties. Withdrawals made prior to age 59 1/2 may incur a 10% IRS federal tax penalty in addition to ordinary income taxation. Index annuity participation rates, interest caps, and spread fees are subject to contractual reset by the issuing carrier at designated renewal periods.
Hypothetical Illustrations & Tax Advice Disclaimer: Case illustrations, mathematical matrices, and sample cash-flow models displayed on this website are hypothetical in nature, provided for educational and analytical purposes only, and do not represent actual client performance or contractual guarantees. Consultation Strategic Wealth Partners LLC does not provide formal legal or certified tax advice. Prospective clients must consult independent qualified CPAs or estate attorneys regarding individual tax status.
Denney Pugmire
Life Insurance Advisor
Phone: 801-390-0887
Website: https://denpuglifecoverage.com/denpuglifeinsurance
NPN: 6236605
Business address: 535 S 200 E, Apt 816, Salt Lake City, UT 84111
Advisory & Fiduciary Standard: Advisory services are offered through Consultation Strategic Wealth Partners LLC, a Registered Investment Adviser. Fiduciary obligations apply strictly when providing individualized investment advisory services under an executed advisory agreement. Insurance products, including fixed index and multi-year guaranteed annuities, are offered through affiliated licensed insurance agents and independent broker partnerships.
(c) 2026 Consultation Strategic Wealth Partners LLC. All rights reserved. | Form ADV Part 2A Brochure | Privacy Policy | Terms of Engagement | FINRA BrokerCheck