OUR EDUCATIONAL PHILOSOPHY
Knowledge Brings Clarity
Insurance has historically been framed as an unavoidable burden: dense policies, opaque terminology, and high-pressure recommendations designed to confuse rather than inform. It is completely natural to feel overwhelmed when navigating complex financial structures alone.
We believe insurance is not a burden; it is an intelligent preparedness strategy. When you understand the underlying mechanics, every decision shifts from uncertainty to quiet confidence. Our resource library exists to provide transparent, unvarnished insight so you can evaluate options on your own terms.
Objective Literacy
Clear frameworks without sales agendas, jargon, or pressure.
Strategic Foresight
Structuring coverage as an active wealth preserver, not an afterthought.
Informed Autonomy
Empowering you to make decisive selections grounded in evidence.
Unbiased, educational publications designed for thorough self-evaluation.
EXCLUSIVE RESOURCE VAULT
CURATED EXECUTIVE INTELLIGENCE
Explore authoritative research briefs, risk mitigation blueprints, and structural wealth frameworks created specifically for executive decision makers and family offices.
General Life Insurance
LIFE INSURANCE
A plain-English guide to what life insurance is, how term and permanent coverage differ, and common factors people consider when choosing an amount and length of coverage.
First-Time Life Insurance Buyers
LIFE INSURANCE
A beginner-friendly walkthrough of how the application process works, what underwriting typically reviews, and how to compare policies and riders without getting overwhelmed.
Final Expense Life Insurance
LIFE INSURANCE
Learn what final expense coverage is designed to address, common use-cases (like funeral and end-of-life costs), and key questions to ask when exploring options.
Mortgage Protection Life Insurance
LIFE INSURANCE
An educational overview of how life insurance may be used as part of a strategy to help protect a family’s mortgage obligations, including term length considerations and beneficiary planning.
Multiple Life Insurance Policy Review
LIFE INSURANCE
Understand why some people “layer” coverage (group + individual, term + permanent), how to avoid gaps or unnecessary overlap, and what to review as your life changes.
Very Large Life Insurance
LIFE INSURANCE
A practical guide to considerations involved with larger policy amounts (often $1M+), including financial documentation, underwriting expectations, and planning uses like business continuity or estate coordination.
Diabetes & Life Insurance
HEALTH & SPECIALIZED
Educational information on how diabetes may be evaluated during underwriting—common lab markers, treatment history, and documentation that can help an application be reviewed accurately.
Cancer & Life Insurance
HEALTH & SPECIALIZED
Learn how a cancer history is commonly considered in life insurance underwriting, including treatment timelines, follow-up care, and questions to discuss with a licensed insurance professional.
Healthy Weight & Life Insurance
HEALTH & SPECIALIZED
A clear explanation of how weight-related factors (like build, labs, and overall health profile) may be reviewed during underwriting, plus practical tips for preparing for an application.
Heart Attacks & Life Insurance
HEALTH & SPECIALIZED
Explore common underwriting considerations for applicants with a heart attack history—time since event, medications, follow-up testing, and what medical records may be requested.
Kidney Disease & Life Insurance
HEALTH & SPECIALIZED
An educational guide to how kidney-related conditions may be assessed, including common labs, stages, and the importance of accurate medical history when exploring coverage options.
Strokes & Life Insurance
HEALTH & SPECIALIZED
Understand typical underwriting questions after a stroke or TIA, including risk factors, follow-up care, and how carriers may evaluate stability and overall health.
Keyman Insurance & Business Succession
OTHER
Learn how key person (keyman) insurance can help businesses plan for the financial impact of losing a critical owner, executive, or revenue-producing employee—plus common ownership and beneficiary structures.
Small Business Health & Life Insurance
OTHER
An overview of benefit options small employers often explore (especially under 50 employees), including group health basics, employer-sponsored life insurance, and voluntary benefit add-ons.
Family Protection & Planning
OTHER
A practical preparedness resource covering beneficiaries, wills, organizing key documents, funeral planning considerations, and steps families can take to be better prepared for the unexpected.
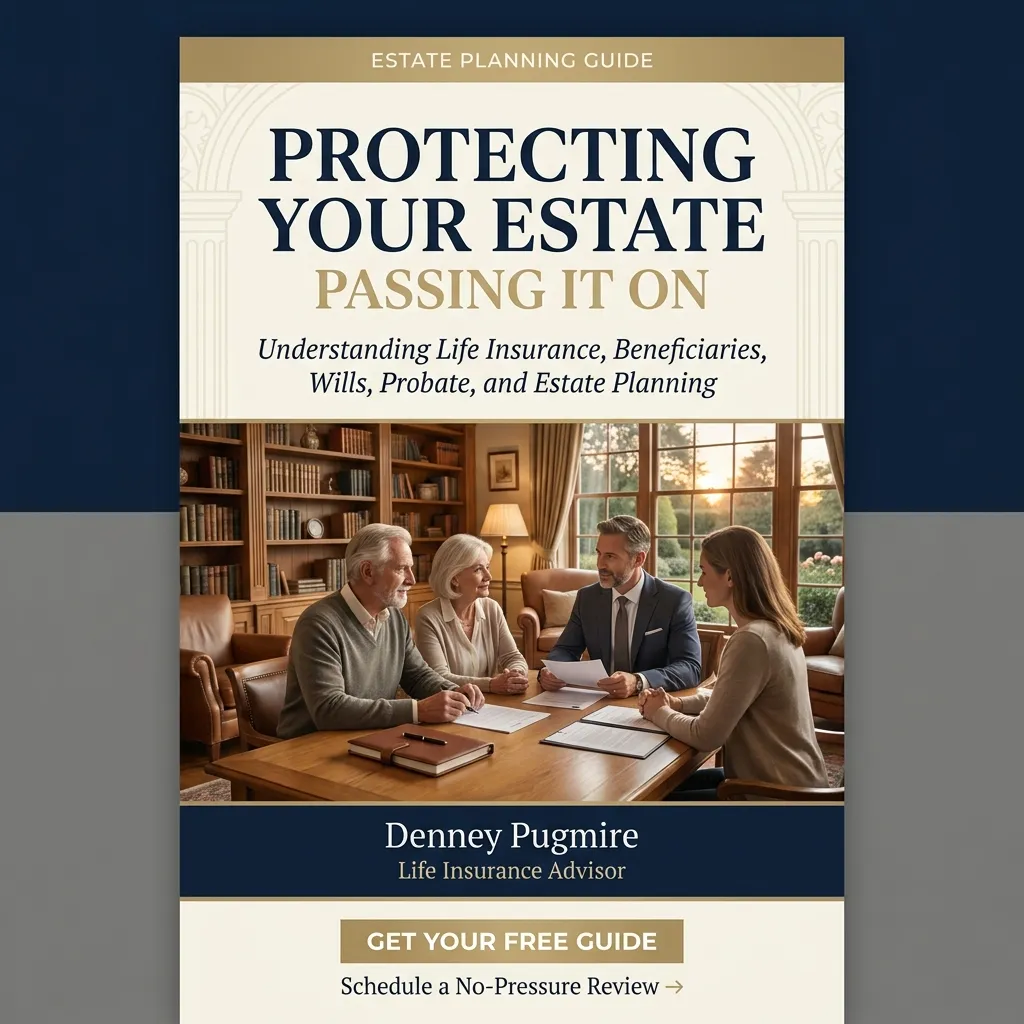
Protecting Your Estate & Passing It On
OTHER
An educational look at how life insurance, beneficiary designations, wills, and probate can work together—plus planning questions to discuss with appropriately licensed legal and financial professionals.
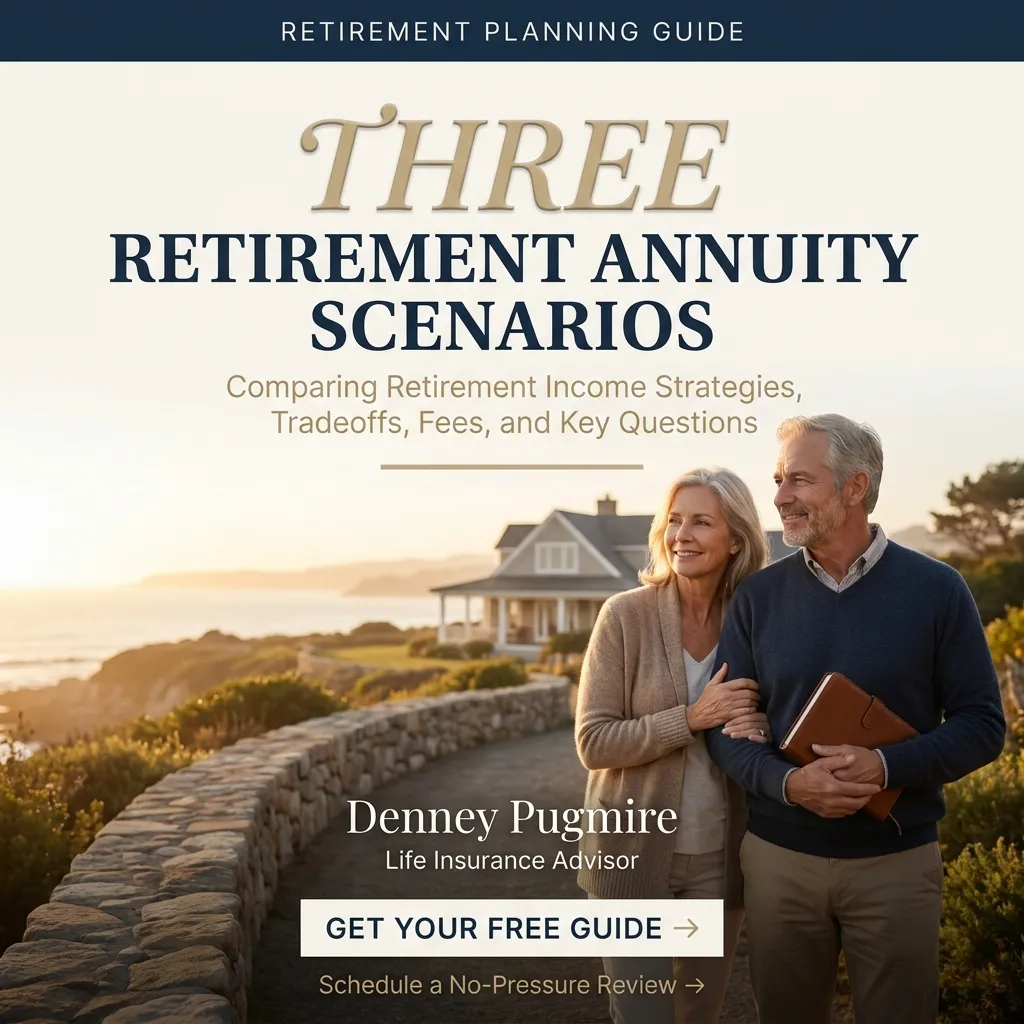
Three Retirement Annuity Scenarios
ANNUITIES & RETIREMENT
Compare three common annuity planning scenarios and learn how different annuity types may be used for retirement income planning—along with key tradeoffs, fees, and questions to ask.
THE PURPOSE BEHIND THE LIBRARY
Knowledge For Real-Life Decisions
Insurance and wealth preservation should not be shrouded in jargon. These comprehensive guides are crafted to give you total clarity, confidence, and actionable control over your financial horizon.
Understand Your Options
Navigate complex coverage structures, policy tiers, and underwriting terms with clear frameworks that remove the guesswork.
Prepare for the Unexpected
Anticipate market shifts, health transitions, and liquidity demands before they emerge to ensure seamless continuity.
Protect Your Family & Business
Shield multi-generational estates, key enterprise personnel, and core assets with fortified risk mitigation strategies.
Make More Informed Decisions
Move from hesitation to decisive action with data-backed perspectives that align perfectly with your wealth objectives.
PATHWAYS OF PROTECTION
Tailored For Your Journey
Explore curated intelligence, institutional-grade insights, and tactical guides tailored specifically to your financial stage and legacy objectives.
Individuals
Building foundational wealth, income protection, and tax-advantaged growth strategies during peak earning years.
- Income replacement & disability
- Term vs. Permanent coverage
- Tax-advantaged cash accumulation
Families
Securing multi-generational stability, funding education, and bypassing stressful probate proceedings seamlessly.
- Probate avoidance strategies
- College legacy endowment trusts
- Survivorship & family liquidity
Business Owners
Shielding enterprise valuation, protecting against key-person loss, and structuring tax-optimized executive benefits.
- Buy-sell agreement funding
- Key person executive indemnity
- Executive bonus plan (162) setups
Retirement Planners
Guaranteeing lifelong income, mitigating sequence-of-returns risk, and preserving principal from market volatility.
- Guaranteed lifetime annuity streams
- Long-term care asset riders
- Sequence-of-returns buffers
VERIFIED CREDENTIALS & ADVISORY STANDARD
Experienced. Licensed.
Independently Representing Your Best Interests.
With access to 15+ insurance companies and licensing across 19 states, Denney Pugmire helps individuals, families, and business owners explore insurance solutions based on their unique needs.
15+
INSURANCE COMPANIES
Access to 15+ Insurance Carriers
Denney works with multiple insurance companies, providing clients with access to a broader range of insurance products and potential solutions rather than being limited to a single carrier.
Carrier availability varies by state and product; eligibility is subject to underwriting.
19
STATES LICENSED
Licensed in 19 States
Denney is licensed to offer insurance solutions in 19 states, allowing him to serve clients across a broad geographic area.
Jurisdiction Scope: 19 States
NPN
PRODUCER NUMBER
National Producer Number (NPN)
NPN: 6236605
Verify licensing and producer information through the appropriate state insurance regulator or official insurance licensing resources.
$1M / $3M
E&O COVERAGE
$1M / $3M Errors & Omissions Coverage
E&O Coverage: $1,000,000 / $3,000,000
Professional Errors & Omissions coverage through NAPA provides additional protection associated with professional insurance activities.
E&O coverage is not a guarantee of outcomes, approvals, or policy performance.
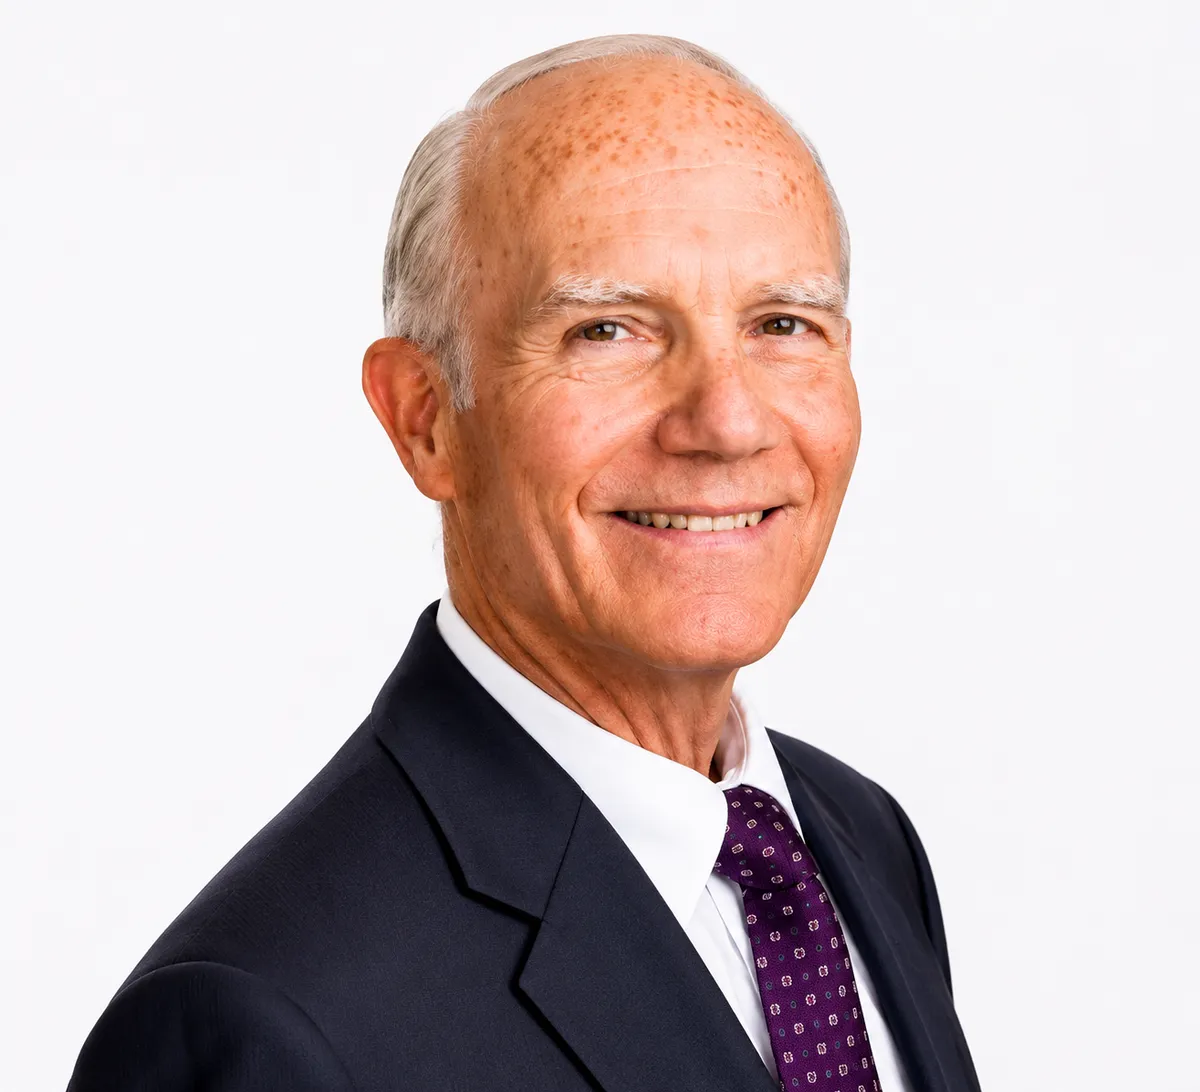
Add Denney’s approved professional headshot
INDEPENDENT FIDUCIARY MINDSET
Meet Denney Pugmire
Denney Pugmire is a licensed insurance professional focused on helping individuals, families, and business owners understand their insurance options and prepare for the future.
Rather than taking a one-size-fits-all approach, Denney works with clients to understand their goals, circumstances, and protection needs before exploring available insurance solutions.
Through relationships with 15+ insurance companies and licensing across 19 states, Denney can help clients compare available options and identify solutions that may fit their situation.
Insurance decisions deserve more than a one-size-fits-all approach.
Access to multiple carriers, broad state licensing, professional credentials, and Errors & Omissions coverage are part of Denney’s commitment to providing a professional insurance experience.
Licensing, producer information, insurance carrier availability, and professional coverage are subject to applicable state requirements and current records. Please contact us for the most current information.
PROFESSIONAL ADVISORY COLLABORATION
A Trusted Insurance Resource
for Accountants & CPAs
When Your Clients Have Insurance Needs, You Can Bring in an Insurance Professional Without Taking Away From Your Role as Their Trusted Advisor.
Accountants and CPAs often have a detailed understanding of their clients' businesses, finances, tax situations, and long-term goals. When life insurance, business protection, retirement planning, or employee benefits become part of the conversation, Denney Pugmire can serve as the insurance resource your clients need.
Denney works alongside existing professional advisors to help clients understand their insurance options while allowing you to remain focused on your area of expertise.
Support Your Clients
Give your clients access to a licensed insurance professional when insurance becomes part of their financial or business planning needs.
Complement Your Practice
Add an insurance resource to your professional network without changing the services or advice you provide to your clients.
Work as a Team
Denney can coordinate with accountants, CPAs, attorneys, financial professionals, and other trusted advisors when insurance is part of a client's broader financial picture.
When an Insurance Referral May Make Sense
- A business owner needs key person or business life insurance
- A client is reviewing estate planning and beneficiary needs
- A client is approaching retirement and evaluating annuity or income options
- A business is exploring health and life insurance for employees
- A client wants a second look at existing life insurance coverage
- A client has a complex health history and wants to understand possible life insurance options
- A client is experiencing a major financial or family life change and needs to review their protection strategy
Have a Client Who Needs an Insurance Review?
Refer them to Denney for a professional insurance conversation while you continue serving them in your area of expertise.
COMPLIMENTARY ADVISORY CONVERSATION
Ready to Explore Your
Insurance Options?
Get a personalized conversation with Denney and learn which insurance options may be available based on your goals and circumstances.
Independent Advisory • No Obligation • Fiduciary Standards
OBJECTIVE ADVISORY ARCHIVE
Clear Answers
Navigating commercial and personal underwriting shouldn't require decoding opaque contract language. Review unbiased fundamentals on liquidity structures, medical risk assessments, and asset preservation.
Independent analysis : No sales obligations
What is life insurance and how does it fundamentally operate?
Life insurance is a binding legal contract between an individual or entity and an insurance carrier. In exchange for regular premium payments, the insurer commits to paying a designated death benefit to specified beneficiaries upon the insured individual's death. Structurally, these contracts serve either as pure death-benefit risk transfers over fixed durations (Term) or permanent wealth accumulation and transfer vehicles (Whole Life, Universal Life).
What is Key Person (Keyman) insurance and who owns the policy?
Key Person insurance is a corporate-owned policy taken out on essential executives, technical founders, or primary revenue generators whose unexpected absence would inflict direct financial or operational harm on the firm. The company pays all scheduled premiums and serves as the sole beneficiary, utilizing the tax-free death benefit proceeds to offset hiring expenses, stabilize commercial credit lines, or facilitate a structured buyout.
Can someone with a pre-existing health condition still qualify for coverage?
Yes. Qualification depends entirely on clinical stability, historical medical documentation, and the specific underwriting matrix of the carrier. While high-risk profiles may incur a 'table rating' (surcharge percentage on standard baseline premiums) or require specialized clinical underwriting, many conditions like controlled hypertension, managed Type 2 diabetes, or historical treated cancers routinely obtain standard or near-standard approvals across modern tier-one carriers.
How does Mortgage Protection insurance differ from standard individual term life?
Mortgage Protection Insurance (MPI) is typically a declining-balance policy designed to pay off only the remaining mortgage principal, with the lending institution often named as the direct beneficiary. Conversely, an individually owned Term Life policy maintains a level death benefit for its entire term, pays proceeds directly to your chosen beneficiaries tax-free, and leaves full discretion to surviving family members regarding debt settlement or estate preservation.
What core metrics determine individual underwriting classifications?
Actuaries and underwriters evaluate age, biological sex, comprehensive medical history, prescription drug databases (MIB checks), resting biometrics (BMI, blood pressure, cholesterol ratios), family medical longevity (cardiac or oncological history prior to age 60), occupational risk exposure, and foreign travel frequency. These metrics determine your final risk tier: Preferred Plus, Preferred, Standard Plus, Standard, or Substandard/Rated.
Are life insurance death benefit proceeds taxable to the beneficiary?
Under Internal Revenue Code Section 101(a), death benefit proceeds paid to a designated individual beneficiary are generally exempt from federal and state ordinary income taxes. However, interest accrued if proceeds are held in carrier retained accounts is taxable, and policies held within an estate exceeding statutory unified exemption thresholds may become subject to federal or state estate taxation unless held in an Irrevocable Life Insurance Trust (ILIT).
What is the difference between Term Life and Permanent Whole Life insurance?
Term Life provides pure, unbundled death benefit protection for a predetermined window (typically 10 to 30 years) with zero cash value build-up, making it cost-effective for debt protection and income replacement during peak earning years. Permanent Whole Life provides lifelong coverage, guaranteed level premiums, and a tax-deferred cash value component that grows via guaranteed contractual rates and non-guaranteed carrier dividends.
What is Cash Surrender Value and how can policyholders access it?
Cash surrender value is the accumulated contractual reserve inside a permanent policy, net of administrative expenses and surrender charges. Policyholders can access these funds via tax-free policy loans (borrowing against the cash balance using the policy as collateral), partial surrenders, or a total cancellation of the contract. Unrepaid loans reduce the final death benefit dollar-for-dollar alongside accrued interest.
Why is employer-provided group life insurance often insufficient on its own?
Group coverage is usually capped at a modest multiple of base salary (e.g., 1x to 2x earnings), which often falls well short of comprehensive multi-year debt and income replacement needs. More critically, group life is rarely portable; leaving or losing employment terminates coverage immediately, leaving individuals forced to seek private underwriting at an older age or with newly emerged health complications.
What policy riders should be evaluated during contractual drafting?
Common contractual riders include Accelerated Death Benefit (accessing 50% to 80% of death benefits early upon terminal or chronic illness diagnosis), Waiver of Premium (waiving premium obligations if the insured suffers total disability), Guaranteed Insurability (allowing future coverage increases without subsequent medical exams), and Child Term Riders.
How frequently should an established insurance portfolio be audited?
Institutional guidelines recommend formal portfolio reviews every 24 to 36 months, or immediately following material liquidity events, corporate restructuring, marital status changes, property acquisitions, or significant adjustments to corporate executive compensation packages. Audits verify carrier solvency ratings, term conversion expiry dates, and beneficiary alignment with current estate objectives.
PROTECTING WHAT MATTERS MOST
Your Future Deserves a Plan
Don't leave your family's financial security or enduring legacy to uncertainty. Explore our comprehensive editorial vault of authoritative guides and gain complete strategic clarity.
Instant Vault Access • 100% Free • Comprehensive Educational Resources • No Credit Card Required
Elite Shield | Educational Resource Library
Educational Disclaimer: All content, ebooks, calculators, and materials published by Elite Shield are provided exclusively for educational and informational purposes. Nothing contained herein constitutes financial, investment, tax, legal, or estate planning advice. Policy details, rates, and coverage provisions vary by carrier, jurisdiction, and underwriting guidelines. Consult a licensed independent insurance professional or certified financial advisor prior to executing any contract.
© 2026 Elite Shield. All rights reserved. Registered Insurance Education & Consumer Guidance Network.
LIBRARY NAVIGATION
COMPLIANCE & LEGAL
Security Standards: 256-Bit SSL Encrypted Vault | Strict Zero-Spam Commitment | SOC-2 Compliant Privacy Protections