EXISTING COVERAGE INSIGHTS
Can You Have Multiple
Life Insurance Policies?
Yes, holding multiple life insurance policies is entirely legal and often advantageous. However, approval depends on your total insurable financial need, verified income limits, and carrier underwriting standards across all active coverage.
Independent analysis · Carrier availability and approval subject to state regulations and underwriting guidelines.
POLICY FUNDAMENTALS
Understanding Multiple
Policy Ownership
Clear, objective guidance on legal guidelines, total insurable capacity, and strategic reasons individuals hold more than one life contract.
Can You Have More Than One?
Yes. There is no legal ceiling on how many life insurance policies an individual can own concurrently. Insurance carriers evaluate total risk through financial underwriting rather than contract quantity.
Underwriters assess your total earned income, existing liabilities, and net worth to establish your total allowable coverage limit. As long as the cumulative death benefit aligns with your legitimate financial justification, holding policies across multiple carriers is standard practice and completely legal.
* All applications require full disclosure of existing policies to ensure transparent carrier underwriting.
Why Someone Might Have Multiple Policies
Coverage needs evolve alongside life milestones. Rather than replacing a favorable locked-in rate, policyholders frequently layer supplemental coverage as obligations expand:
• Life Stage Changes: Supplementing early term policies following marriage, higher mortgage debt, or expanding families.
• Business Protection: Establishing buy-sell agreements or key person insurance separate from personal estate plans.
• Layered Duration & Costs: Combining short-term term life for child dependency years with permanent coverage for legacy transfer.
PORTFOLIO ARCHITECTURE
Common Combinations
of Coverage
Structuring multiple policies allows tailored protection across distinct financial milestones without paying for redundant lifelong premiums.
Multiple Term Policies
Often called a 'laddering strategy' to match declining debts such as mortgages and college tuition.
- Staggers 10, 20, and 30-year terms to lower long-term cost
- Reduces overall coverage automatically as debts are paid down
- Significantly cheaper than purchasing one massive permanent policy
- Provides high financial leverage during peak liability years
Multiple Permanent Policies
Designed for long-range estate preservation, tax-deferred growth, and business succession continuity.
- Guarantees permanent death benefit regardless of advanced age
- Diversifies cash value accumulation across whole life and universal structures
- Supplements estate liquidity to offset inheritance and capital taxes
- Protects business equity through structured buy-sell agreements
Employer + Individual
Fills critical portability and benefit gaps left by basic employer-provided group life plans.
- Maintains individual coverage independently of job transitions or layoffs
- Elevates total payout above standard employer caps (often 1-2x salary)
- Locks in personal insurability ratings early while health is optimal
- Leverages free workplace base coverage to keep supplemental rates modest
ANALYTICAL FRAMEWORK
Strategic Considerations
For Additional Coverage
Expanding your life insurance portfolio should always be the result of disciplined calculation rather than speculative urgency. Evaluate the critical milestones and structural safeguards below.
PORTFOLIO TRIGGERS
When Additional Life Insurance May Be Considered
Life events frequently outpace static benefit limits. When financial responsibilities expand substantially, layering a supplemental contract often provides tailored coverage without surrendering favorable terms on existing policies.
- Substantial income growth creating an unprotected income replacement gap
- New debt commitments, mortgages, or personal business guarantees
- Arrival of new children or long-term dependent family obligations
- Expiring group benefits or transitions between employer programs
DUE DILIGENCE PROTOCOL
What to Review Before Adding Another Policy
Before committing capital to new premiums, an objective audit verifies whether adding capacity aligns with your long-term cash flow and estate strategy.
- Total cumulative premium affordability across changing market cycles
- Proper beneficiary structuring and ownership rights (personal vs trust)
- Conversion privileges and laddering duration on current term products
- Underwriting requirements and potential insurable interest limits
RESPONSIBLE PORTFOLIO STEWARDSHIP
Take Inventory of Your
Existing Coverage
Life changes quickly, but insurance portfolios often remain static. An unexamined mix of employer group life, individual term policies, and older permanent plans frequently results in overlapping premium costs, outdated beneficiary designations, or unaddressed protection gaps.
A structured review is not a sales solicitation: it is an objective fiduciary assessment to verify that every dollar allocated to insurance actively serves your current wealth preservation and family legacy goals.
Independent analysis with zero purchase obligation. Policies remain unchanged unless you explicitly request a restructure.
FIDUCIARY AUDIT SCOPE
What We Evaluate During an Existing Coverage Review
Worksheet Deliverable: You receive an aggregated one-page summary detailing current death benefits, total monthly premium outlay, and active conversion options across all carriers.
PROFESSIONAL FIDUCIARY STANDARDS
Independent Advocacy
Structuring multiple insurance policies requires analytical rigor and zero carrier bias. Denney Pugmire provides independent oversight centered entirely on your balance sheet.
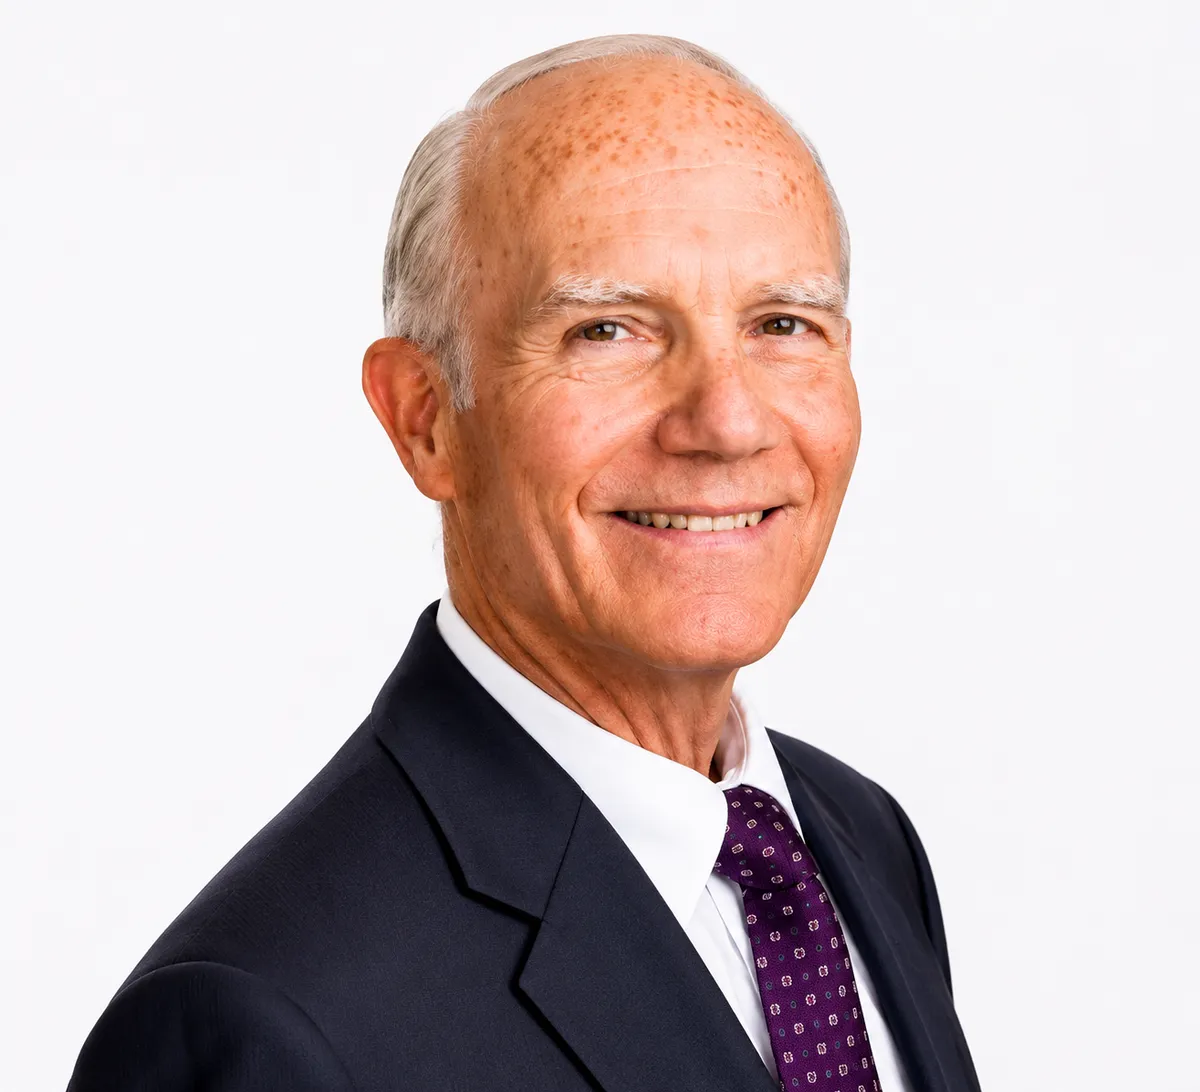
Denney Pugmire
Principal Advisor & Multi-Policy Strategist
Dedicated to bringing institutional-grade clarity and objective underwriting analysis to complex personal and corporate coverage stacks.
Licensed Agent
Direct state licensure authorizing multi-state underwriting, policy evaluation, and fiduciary portfolio optimization.
Fiduciary Standard
Ethically bound to prioritize your financial interests first - eliminating conflicting sales quotas and bias.
Independent Agent Model
Free from captive carrier mandates, ensuring objective comparison across all available policy structures.
15+ Top-Rated Carriers
Direct market access to tier-one mutuals and leading institutional carriers to negotiate optimal rates.
THE ADVISOR ROADMAP
The Consultation Journey
A structured, non-sales diagnostic designed to bring absolute clarity to your life insurance portfolio. No high-pressure tactics, no mandatory policy replacements, just straightforward fiduciary guidance.
No obligation to buy or alter existing policies. Independent fiduciary guidance.
Insurance advisory services provided by Denney Pugmire. Policy approvals, pricing, and underwriting terms are subject to carrier guidelines.
UNDERWRITING & STRATEGY INSIGHTS
Common Questions
Understand the regulatory principles, underwriting realities, and strategic logic behind managing multiple life insurance contracts.
Can you legally own more than one life insurance policy?
Yes. There is no statutory limit on the number of individual life insurance contracts one person can hold. Many individuals maintain separate policies across different carriers to address distinct financial obligations, such as family income replacement, business succession, or inheritance planning.
Can you have two term life insurance policies at the same time?
Yes. A strategy known as policy laddering involves taking out multiple term policies with staggered durations (for instance, a 10-year policy alongside a 20-year policy). This allows you to hold maximum coverage during peak liability years, such as mortgage payoff or college funding, while reducing overall lifetime premium costs as debt declines.
How does employer-provided group life insurance compare to individual coverage?
Employer-sponsored life insurance is typically convenient and often subsidized, but coverage amounts are generally capped (commonly 1x-2x salary) and terminate if you change jobs. Individual coverage remains entirely under your personal control, is fully portable regardless of employment changes, and allows customizable benefit structures tailored to your specific liabilities.
Is there a maximum limit on how much total coverage you can purchase?
While there is no legal ceiling on policy count, insurance carriers enforce underwriting limits based on financial justification. Underwriters calculate allowable coverage using income replacement multipliers (often 10x-30x annual income depending on age) and net worth guidelines to ensure the total cumulative death benefit across all active policies aligns proportionally with demonstrable financial risk.
Should I consider buying an additional life insurance policy?
Purchasing an additional policy makes sense when major life transitions occur: acquiring real estate debt, expanding your family, launching a business, or exhausting group benefit limits. Rather than replacing a favorable existing rate, adding a supplemental policy lets you match new liabilities without forfeiting historical pricing.
Educational Notice: Information provided is for instructional purposes only. Policy issuance, underwriting approval, allowable death benefit ceilings, and premium structures remain subject to individual medical history, financial justification, state regulation, and carrier-specific guidelines.
INDEPENDENT EVALUATION • ZERO PRESSURE
Ready to Review Your Coverage?
Gain complete clarity on your existing life insurance policies with an independent, objective evaluation. A policy review carries zero obligation to alter or purchase coverage: our sole purpose is verifying that your benefits, riders, and beneficiaries align precisely with your long-term family goals.
Denney Pugmire is an independent licensed life insurance advisor. An existing coverage review is strictly an educational analysis and carries no requirement, obligation, or fee to modify, cancel, or purchase coverage. Policy guarantees are backed solely by the financial strength and claims-paying ability of the issuing insurance carriers.
Denney Pugmire
Independent Fiduciary-Standard Life Insurance Advisory & Multi-Policy Architecture
Overview | Policy Comparison | Strategy | Credentials | Process | FAQs


MANDATORY REGULATORY INSURANCE DISCLOSURES & UNDERWRITING NOTICE: Denney Pugmire is an independent licensed life insurance advisor and agent. Life insurance products, policy riders, coverage amounts, and premium rates displayed or discussed across this platform are subject to carrier underwriting approval, individual medical eligibility assessment, age, state jurisdiction, occupation, and carrier-specific underwriting criteria. Information, comparisons, and rate estimations provided on this website are strictly for educational and initial guidance purposes and do not represent a binder of insurance, an offer of coverage, or a guarantee of final premium cost. Actual policy rates and terms are finalized solely by the issuing insurance company upon submission and formal review of an application. Denney Pugmire is not an agency of, nor affiliated with or endorsed by, any federal, state, or local governmental body.
© 2026 Denney Pugmire. All rights reserved. | Privacy Policy | Terms of Service | State Licensing Disclosures